



An estimated €500 million in unclaimed pension savings is sitting untouched across Ireland, money that belongs to ordinary workers who simply lost track of it along the way.
Job changes, house moves and the passage of time all conspire to sever people from retirement savings they legitimately built up over years of employment.
Whether it was a short stint with a company in your 20s or a workplace scheme you contributed to briefly before emigrating, those funds remain yours and tracking them down could prove far more valuable than you might expect.
The process, known formally as pension tracing, involves identifying schemes you contributed to in the past but no longer actively manage.
This can include occupational pensions from former employers, personal pension plans and even schemes built up during periods of employment in the UK. You do not need a full paper trail to begin. Your full name, PPS number and the names of any former employers are often enough to start the search.
Beyond the obvious appeal of finding forgotten money, there are practical financial benefits to bringing old pensions back into view.
Consolidating multiple pension pots into a single arrangement can reduce administrative fees, improve investment oversight and make retirement planning considerably more straightforward. Without a complete picture of your accumulated savings, accurate retirement projections are close to impossible.
The process, however, is rarely simple. Companies close, merge or rebrand. Pension schemes change administrators. Records go missing. In cases involving UK employment, additional cross-border complexity arises.
A qualified financial advisor, authorised to act on your behalf, can contact pension providers directly, access industry databases and navigate these obstacles in a way that most individuals simply cannot do efficiently on their own.
Once located, each pension can be assessed for its current value, terms and available options. Depending on your circumstances, you might choose to leave funds where they are, consolidate them into a Personal Retirement Bond or PRSA or transfer them into your current employer’s scheme.
For those aged 50 and over, partial early access may also be possible, with a portion potentially available as a lump sum, although the tax treatment will depend on the type of scheme, total lifetime pension drawings and individual circumstances. Any such decision carries long-term implications for retirement income and warrants careful consideration.
Tracing old pensions is ultimately an exercise in taking control. The rules governing pensions in Ireland are detailed and, in places, unforgiving of errors.
For most people, the combination of complexity, competing options and real financial stakes makes professional guidance not merely convenient, but essential.
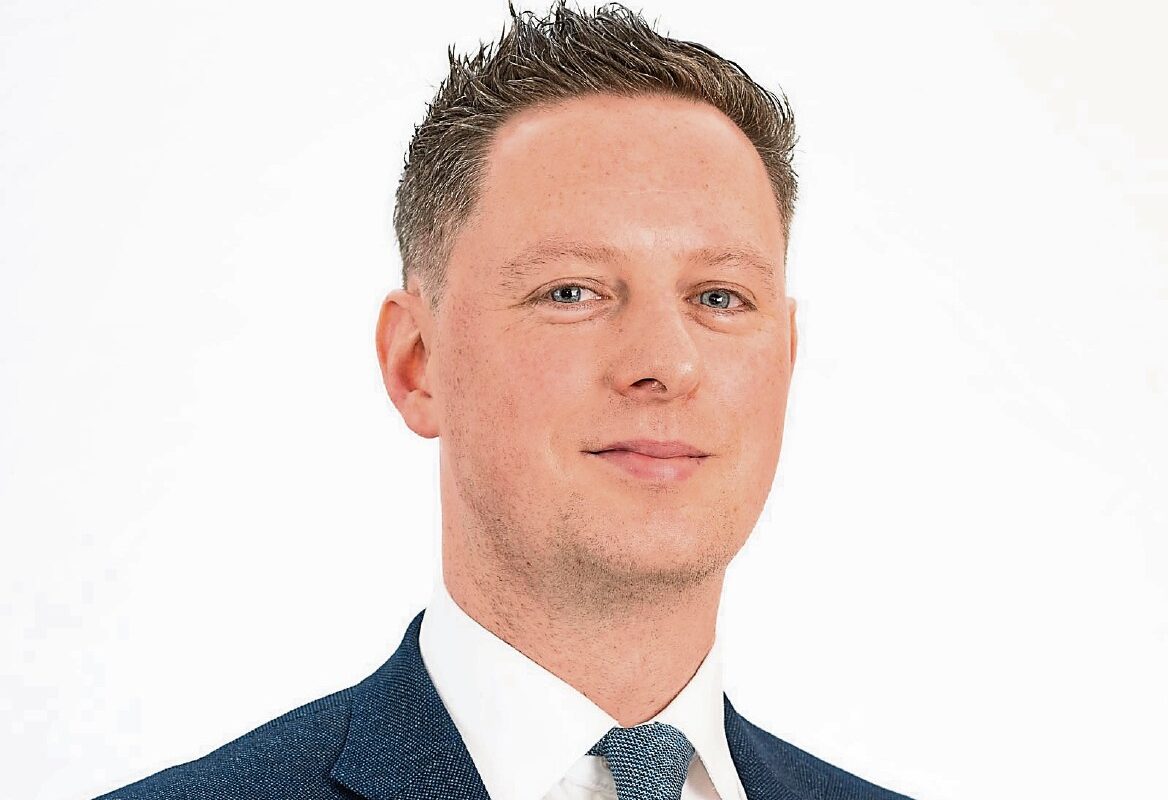
Adrian Kelly, QFA RPA is a Qualified Financial Advisor and Retirement Planning Advisor. You can contact him through Fairstone Letterkenny (formerly John F. Loughrey Financial Services) by telephone on 074-9124002 or by email on [email protected]