



Financial goals are widely recommended, yet many people underestimate their true impact.
In practice, the difference between financial progress and stagnation often comes down to whether there is a clear plan guiding decisions. When goals are properly understood, they shift from being a routine task to a powerful driver of long-term success.
At their core, financial goals give direction to money. Without them, it is easy to earn well, spend freely and still find little to show for it over time.
Defined objectives create a structure that helps individuals make more intentional decisions, ensuring that day-to-day spending and long-term planning are aligned.
A key benefit of goal-setting is that it encourages people to think seriously about what they want from life. Whether the aim is to retire comfortably, own a home or provide security for family members, identifying these priorities is the first step. Without this clarity, financial decisions can become reactive and important ambitions may remain out of reach.
Clear goals also improve decision-making. Financial choices, such as changing jobs, investing savings or making large purchases, can feel overwhelming.
However, when measured against specific objectives, these decisions become easier to assess. Individuals can focus on whether a choice moves them closer to or further from their goals, leading to greater confidence and consistency.
In addition, financial goals help reduce decision fatigue. With so many options competing for attention, it is easy to feel stuck or unsure. Goals act as a filter, simplifying choices and allowing individuals to focus on what truly matters. This clarity can free up time and mental energy while improving financial discipline.
Setting specific targets also tends to improve financial behaviour. People with clear goals are more likely to save regularly, manage spending and look for ways to grow their income. Over time, this can lead to meaningful outcomes, such as reducing debt earlier or building a stronger financial foundation for retirement.
Another important advantage is improved financial protection. When individuals plan ahead, they are more likely to consider risks and put safeguards in place, such as emergency savings or insurance cover.
While setting goals is essential, achieving them can be complex. Changing financial conditions, tax considerations and personal circumstances all play a role.
For this reason, seeking expert financial advice is crucial. A qualified advisor can help turn broad ambitions into practical, achievable plans tailored to individual needs.
Ultimately, financial success is rarely accidental. Clear goals provide the structure and focus needed to take control of one’s financial future and make steady, confident progress over time.
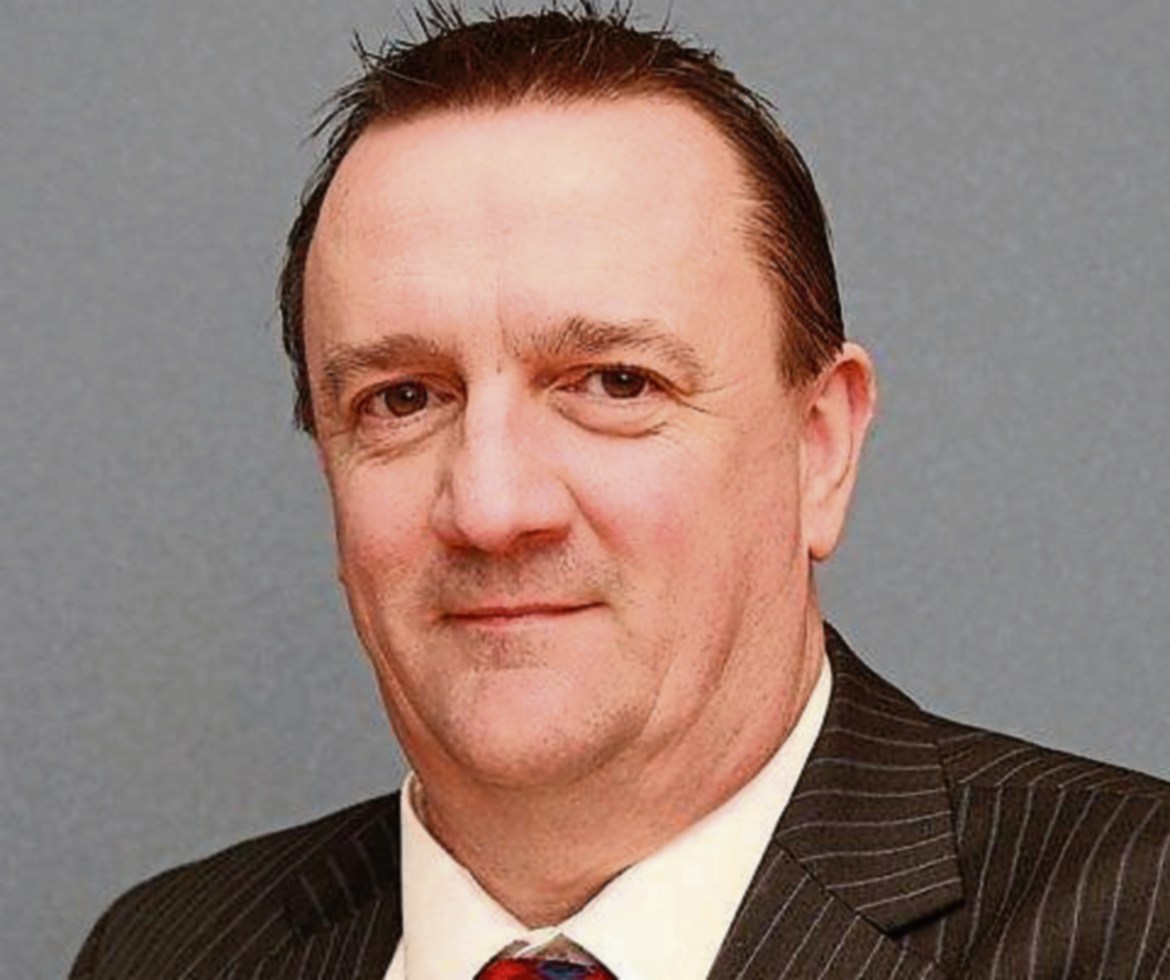
Sean Sweeney, QFA RPA is a Qualified Financial Advisor and Retirement Planning Advisor. You can contact him through Fairstone Letterkenny (formerly John F. Loughrey Financial Services) by telephone on 074-9124002 or by email on [email protected]